
Why ESG Matters: AI and the clean energy transition
24 September 2026
Key takeaways
-
The rapid adoption of artificial intelligence (AI) and the expansion of data centres are creating significant investment opportunities across climate technology.
-
Data centre expansion is expected to encourage greater renewable integration, with renewables potentially accounting for more than half of additional generation capacity by 2035.
-
The long-term success of this investment will depend on managing energy, water and community impacts responsibly.
The data centre boom is driving investment in renewable energy and battery storage, helping to accelerate the energy transition. However, the economic benefits will depend largely on the successful adoption of AI, while rising energy demand and environmental concerns remain key challenges. We look at the role of renewable power purchase agreements, AI technology and efficiency gains, and data centre battery storage demand.
Did you know?
-
On average, at least USD6.3trn per year in climate finance will be needed until 2030 to avoid the worst impacts of climate change.
-
Global energy transition investment has grown at an annual rate of 20% to USD2.3trn over the past 10 years to 2025.
-
The data centre market currently consumes up to 1.5% of global electricity.
-
AI-related private investments in the US rose by 23.5% y-o-y in Q1 2026.
-
By 2030, global data centre onsite battery capacity is estimated to increase by more than 100GW.
-
The technology sector represented 40% of all global corporate renewable power purchase agreements in 2025.
Sources: Climate Policy Initiative, BloombergNEF, Bureau of Economic Analysis, IEA, S&P Global, HSBC
AI driving climate tech investment
The rapid adoption of artificial intelligence (AI) and the expansion of data centres are creating significant investment opportunities across climate technology. Rising electricity demand is expected to support growth in renewable energy, battery storage and electricity network upgrades, particularly in the United States.
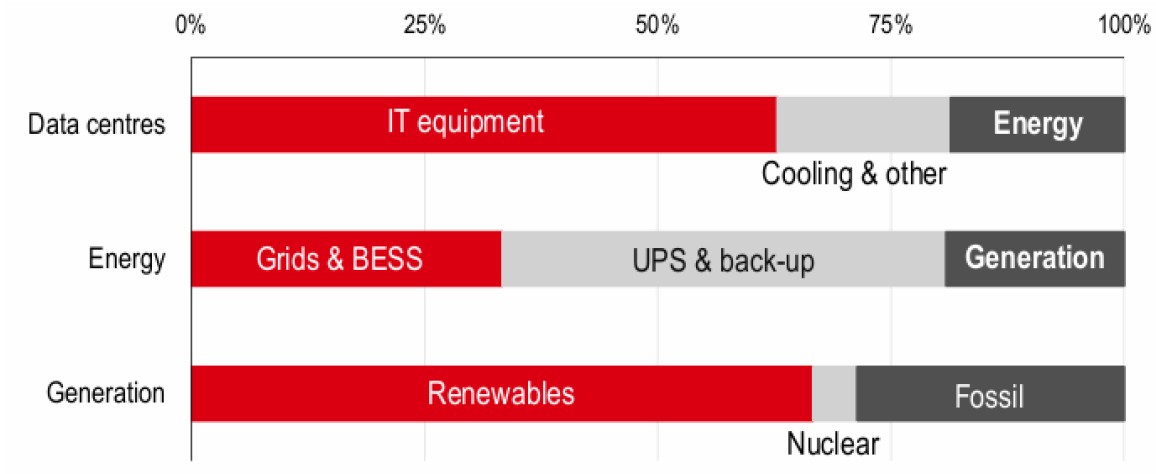
Energy investment linked to US data centre construction reached an estimated USD105bn in 2025, with renewable energy accounting for the majority of energy generation investment (Chart 1). AI investment is also increasing. US private sector investment in AI rose by 23.5% year-on-year in the first quarter of 2026, with this expansion benefitting Asian exporters that supply data centre infrastructure to the United States and other markets.
Australia’s data centre market is also booming, supported by domestic energy supplies and imported equipment. The potential economic benefits include stronger local technology capabilities, wider AI adoption and growth in professional services exports. However, the country faces significant energy and water constraints, with some estimates suggesting that Australia could face an energy shortfall of 40% by 2028[@why-esg-matters-06-01]. Renewable energy development, grid investment and effective water policies will therefore be important to sustain future growth.
In China, glass-based upgrades for AI chip packaging are creating opportunities to improve efficiency and performance. Glass could provide a lower cost alternative to silicon for certain packaging applications, while reducing warping, improving power delivery and lowering electrical resistance. From a sustainability perspective, these advances could support more efficient computing, reduce electricity consumption and limit material waste, helping to lower AI’s overall energy use and carbon footprint.
Chart 1. Global data centre and energy investments (2025)
Source: IEA (2026). Notes: BESS = battery energy storage system, UPS = uninterruptable power supply
Expanding renewable energy agreements
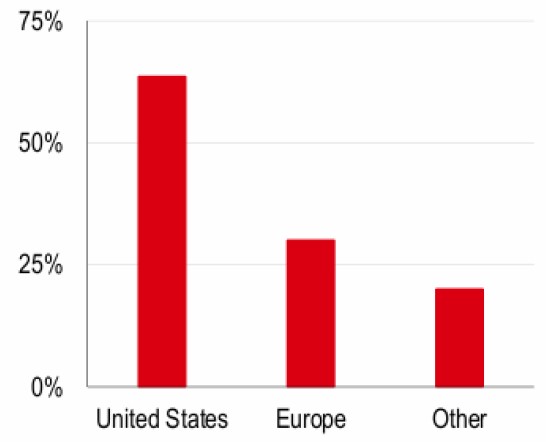
Data centres are increasingly using renewable energy power purchase agreements (PPAs), enabling organisations to buy electricity at an agreed price while supporting clean energy development. Around 40% of renewable PPAs were agreed in the United States in 2024, with approximately 65% supporting data centres over the past five years (Chart 2).
PPA costs could rise as subsidies under the US Inflation Reduction Act are phased out. This coincides with growing electricity demand from AI and data centres, which could make climate targets more difficult to achieve and increase exposure to energy price volatility. Higher costs may also make renewable power less accessible to other industries competing with technology companies.
Nevertheless, technology firms remain significant drivers of renewable energy procurement and investment, accounting for 40% of global corporate renewable PPAs in 2025. Data centres represented almost half of this activity[@why-esg-matters-06-02].
Growing demand for electricity
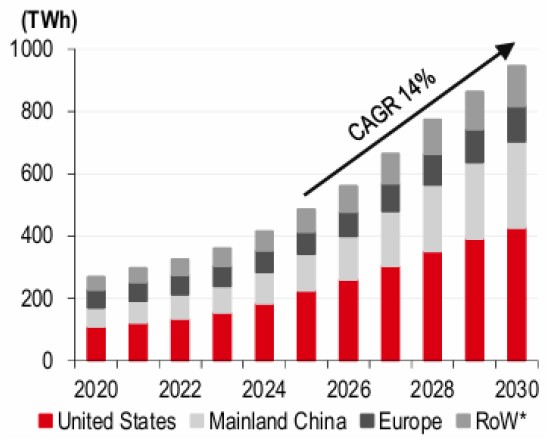
Data centres currently consume up to 1.5% of global electricity. Continued expansion and the localisation of data centres could place further pressure on electricity prices and grid capacity. By 2050, data centres are estimated to require more than 4,000 terawatt-hours of electricity, while in some markets they could account for up to 10% of electricity demand by 2035[@why-esg-matters-06-03].
Fossil fuels currently provide almost 60% of global power[@why-esg-matters-06-04]. However, data centre expansion is expected to encourage greater renewable integration, with renewables potentially accounting for more than half of additional generation capacity by 2035[@why-esg-matters-06-05]. Renewable energy, storage and electricity network investment are therefore likely to benefit from both AI growth and the wider net zero transition.
Chart 2. Data centre share of renewable PPAs by region, 2021-25
Sources: International Energy Agency, S&P Global (2026)
Chart 3. Data centre electricity consumption by region, 2020-30
Source: International Energy Agency (2025)
The role of battery storage
Battery technology is becoming more important as grid constraints and energy supply uncertainty increase. Onsite generation and storage can help data centres access power more quickly, reduce pressure on electricity grids and manage fluctuations in AI-related demand.
Global onsite battery capacity for data centres is expected to increase by more than 100 gigawatts by 2030, with longer duration energy storage systems also expected to expand, rising from 5 gigawatts in 2025 to 25 gigawatts by 2030[@why-esg-matters-06-06].
Public acceptance and sustainability
Communities in several markets are raising concerns about energy affordability, environmental impacts such as water use and employment opportunities. In the United States, proposed moratoriums have emerged in response to concerns about new construction, while, in Europe, campaigns have sought to delay or halt some data centre projects. As energy prices rise, the risk of further increases linked to data centre demand could prompt additional resistance.
Public acceptance will depend on whether developers can provide stable and affordable energy, manage water use responsibly, deliver meaningful local economic benefits, and expand renewable generation and battery storage alongside new data centres. Initiatives such as the United Nations’ AI Environmental Transparency Initiative, which includes environmental disclosures and renewable energy targets, could support more sustainable development by improving transparency around affordability and environmental impacts.
Conclusion
AI and data centres are creating significant opportunities for renewable energy, battery storage, electricity networks and emerging technologies such as geothermal energy and small modular reactors. However, the long-term success of these investments will depend on managing energy, water and community impacts responsibly. Ensuring that AI growth supports cleaner, more resilient and affordable energy systems will be critical to achieving wider climate objectives.

Related Insights


Disclosure appendix
1. This report is dated as at 24 September 2026.
2. All market data included in this report are dated as at close 23 September 2026, unless a different date and/or a specific time of day is indicated in the report.
3. HSBC has procedures in place to identify and manage any potential conflicts of interest that arise in connection with its Research business. HSBC’s analysts and its other staff who are involved in the preparation and dissemination of Research operate and have a management reporting line independent of HSBC’s Investment Banking business. Information Barrier procedures are in place between the Investment Banking, Principal Trading, and Research businesses to ensure that any confidential and/or price sensitive information is handled in an appropriate manner.
4. You are not permitted to use, for reference, any data in this document for the purpose of (i) determining the interest payable, or other sums due, under loan agreements or under other financial contracts or instruments, (ii) determining the price at which a financial instrument may be bought or sold or traded or redeemed, or the value of a financial instrument, and/or (iii) measuring the performance of a financial instrument.
Disclaimer
This document or video is prepared by The Hongkong and Shanghai Banking Corporation Limited (‘HBAP’), 1 Queen’s Road Central, Hong Kong. HBAP is incorporated in Hong Kong and is part of the HSBC Group. This document or video is distributed and/or made available by HSBC Bank (China) Company Limited, HSBC Bank (Singapore) Limited, HSBC Bank Middle East Limited (UAE), HSBC UK Bank Plc, HSBC Bank Malaysia Berhad (198401015221 (127776-V))/HSBC Amanah Malaysia Berhad (20080100642 1 (807705-X)), HSBC Bank (Taiwan) Limited, HSBC Bank plc, Jersey Branch, HSBC Bank plc, Guernsey Branch, HSBC Bank plc in the Isle of Man, HSBC Continental Europe, Greece, The Hongkong and Shanghai Banking Corporation Limited, India (HSBC India), HSBC Bank (Vietnam) Limited, PT Bank HSBC Indonesia (HBID), HSBC Bank (Uruguay) S.A. (HSBC Uruguay is authorised and oversought by Banco Central del Uruguay), The Hongkong and Shanghai Banking Corporation Limited – Philippine Branch, HSBC Investment and Insurance Brokerage, Philippines Inc, HSBC Insurance Brokerage Company Limited, HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group (collectively, the “Distributors”) and HSBC Bank Middle East Limited Qatar Branch, P.O. Box 57, Doha, Qatar (regulated by Qatar Central Bank for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority) to their respective clients. This document or video is for general circulation and information purposes only.
The contents of this document or video may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. This document or video must not be distributed in any jurisdiction where its distribution is unlawful. All non-authorised reproduction or use of this document or video will be the responsibility of the user and may lead to legal proceedings. The material contained in this document or video is for general information purposes only and does not constitute investment research or advice or a recommendation to buy or sell investments. Some of the statements contained in this document or video may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. HBAP and the Distributors do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document or video has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed are based on the HSBC Global Investment Committee at the time of preparation and are subject to change at any time. These views may not necessarily indicate HSBC Asset Management‘s current portfolios’ composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients’ objectives, risk preferences, time horizon, and market liquidity.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. Past performance contained in this document or video is not a reliable indicator of future performance whilst any forecasts, projections and simulations contained herein should not be relied upon as an indication of future results. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries in which they trade. Investments are subject to market risks, read all investment related documents carefully.
This document or video provides a high-level overview of the recent economic environment and has been prepared for information purposes only. The views presented are those of HBAP and are based on HBAP’s global views and may not necessarily align with the Distributors’ local views. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. It is not intended to provide and should not be relied on for accounting, legal or tax advice. Before you make any investment decision, you may wish to consult an independent financial adviser. In the event that you choose not to seek advice from a financial adviser, you should carefully consider whether the investment product is suitable for you. You are advised to obtain appropriate professional advice where necessary.
The accuracy and/or completeness of any third-party information obtained from sources which we believe to be reliable might have not been independently verified, hence customers must seek several sources prior to making investment decisions.
The following statement is only applicable to HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group with regard to how the publication is distributed to its customers: This publication is distributed by Wealth Insights of HSBC México, and its objective is for informational purposes only and should not be interpreted as an offer or invitation to buy or sell any security related to financial instruments, investments or other financial product. This communication is not intended to contain an exhaustive description of the considerations that may be important in making a decision to make any change and/or modification to any product, and what is contained or reflected in this report does not constitute, and is not intended to constitute, nor should it be construed as advice, investment advice or a recommendation, offer or solicitation to buy or sell any service, product, security, merchandise, currency or any other asset.
Receiving parties should not consider this document as a substitute for their own judgment. The past performance of the securities or financial instruments mentioned herein is not necessarily indicative of future results. All information, as well as prices indicated, are subject to change without prior notice; Wealth Insights of HSBC Mexico is not obliged to update or keep it current or to give any notification in the event that the information presented here undergoes any update or change. The securities and investment products described herein may not be suitable for sale in all jurisdictions or may not be suitable for some categories of investors.
The information contained in this communication is derived from a variety of sources deemed reliable; however, its accuracy or completeness cannot be guaranteed. HSBC México will not be responsible for any loss or damage of any kind that may arise from transmission errors, inaccuracies, omissions, changes in market factors or conditions, or any other circumstance beyond the control of HSBC. Different HSBC legal entities may carry out distribution of Wealth Insights internationally in accordance with local regulatory requirements.
Important Information about the Hongkong and Shanghai Banking Corporation Limited, India (“HSBC India”): HSBC India is a branch of The Hongkong and Shanghai Banking Corporation Limited. HSBC India does not distribute or refer investment products to those persons who are either the citizens or residents of United States of America (USA), Canada or any other jurisdiction where such distribution or referral would be contrary to law or regulation.
HSBC India is an AMFI-registered Mutual Fund Distributor and an AMFI-registered Specialized Investment Fund (SIF) Distributor. HSBC India distributes select mutual fund schemes and SIF strategies of empaneled Asset Management Companies, and acts as a referrer of other third-party investment products. Mutual Fund investments are subject to market risks, read all scheme-related documents carefully. AMFI-registered Mutual Fund Distributor | Date of Initial Registration: 19 Feb 2002 | ARN-0022 I Validity of ARN: 18 Feb 2027. AMFI-registered SIF Distributor I Date of initial registration: 27 Oct 2025 | ARN-0022 I Validity of ARN: 26 Oct 2028.
HSBC India will receive commission from HSBC Asset Management (India) Private Limited, in its capacity as a AMFI registered mutual fund distributor of HSBC Mutual Fund. The Sponsor of HSBC Mutual Fund is HSBC Securities and Capital Markets (India) Private Limited (HSCI), a member of the HSBC Group. Please note that HSBC India and the Sponsor being part of the HSBC Group, may give rise to real, perceived, or potential conflicts of interest. HSBC India has a policy in place to identify, prevent and manage such conflict of interest. For more information related to investments in the securities market, please visit the SEBI Investor Website: https://investor.sebi.gov.in/ and the SEBI Saa₹thi Mobile App.
The following statement is only applicable to HSBC Bank (Taiwan) Limited with regard to how the publication is distributed to its customers: HSBC Bank (Taiwan) Limited (“the Bank”) shall fulfill the fiduciary duty act as a reasonable person once in exercising offering/conducting ordinary care in offering trust services/ business. However, the Bank disclaims any guarantee on the management or operation performance of the trust business.
The following statement is only applicable to PT Bank HSBC Indonesia (“HBID”): HBID is licensed and supervised by Indonesia Financial Services Authority (“OJK”). Investment products that are offered in HBID are third party products, HBID is a selling agent for third party products such as Mutual Funds and Bonds. HBID and HSBC Group (HSBC Holdings Plc and its subsidiaries and associates company or any of its branches) do not guarantee the underlying investment, principal or return on customer’s investment. You must read and understand the investment policy of each investment product to see if a product contains ESG and sustainability elements and is classified as an ESG and sustainable investment. Investment in Mutual Funds and Bonds are not covered by the deposit insurance program of the Indonesian Deposit Insurance Corporation (“LPS”).
Important information on ESG and sustainable investing
Today we finance a number of industries that significantly contribute to greenhouse gas emissions. We have a strategy to help our customers to reduce their emissions and to reduce our own. For more information visit www.hsbc.com/sustainability.
In broad terms “ESG and sustainable investing” products include investment approaches or instruments which consider environmental, social, governance and/or other sustainability factors to varying degrees. Certain instruments we classify as sustainable may be in the process of changing to deliver sustainability outcomes. There is no guarantee that ESG and Sustainable investing products will produce returns similar to those which don’t consider these factors. ESG and Sustainable investing products may diverge from traditional market benchmarks. In addition, there is no standard definition of, or measurement criteria for, ESG and Sustainable investing or the impact of ESG and Sustainable investing products. ESG and Sustainable investing and related impact measurement criteria are (a) highly subjective and (b) may vary significantly across and within sectors.
HSBC may rely on measurement criteria devised and reported by third party providers or issuers. HSBC does not always conduct its own specific due diligence in relation to measurement criteria. There is no guarantee: (a) that the nature of the ESG / sustainability impact or measurement criteria of an investment will be aligned with any particular investor’s sustainability goals; or (b) that the stated level or target level of ESG / sustainability impact will be achieved. ESG and Sustainable investing is an evolving area and new regulations are being developed which will affect how investments can be categorised or labelled. An investment which is considered to fulfil sustainable criteria today may not meet those criteria at some point in the future.
THE CONTENTS OF THIS DOCUMENT OR VIDEO HAVE NOT BEEN REVIEWED BY ANY REGULATORY AUTHORITY IN HONG KONG OR ANY OTHER JURISDICTION. YOU ARE ADVISED TO EXERCISE CAUTION IN RELATION TO THE INVESTMENT AND THIS DOCUMENT OR VIDEO. IF YOU ARE IN DOUBT ABOUT ANY OF THE CONTENTS OF THIS DOCUMENT OR VIDEO, YOU SHOULD OBTAIN INDEPENDENT PROFESSIONAL ADVICE.
© Copyright 2026. The Hongkong and Shanghai Banking Corporation Limited, ALL RIGHTS RESERVED.
No part of this document or video may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording or otherwise, without the prior written permission of The Hongkong and Shanghai Banking Corporation Limited.